HMRC Mileage Rates 2026: New 55p Rate And Latest Company Car Rates Explained
 Published By
Olivia
Published:
Updated:
Table of Contents
HMRC mileage rates for 2026 have changed significantly, with employees and self-employed workers now able to use a 55p-per-mile rate for the first 10,000 qualifying business miles travelled in their own car or van.
The rate increased from 45p to 55p for the 2026/27 tax year and was backdated to 6 April 2026, meaning eligible journeys made since the start of the tax year can fall under the higher figure. The rate for business mileage above 10,000 miles remains at 25p.
It is the first increase to the main car and van mileage rate since 2011, after years in which fuel, insurance, servicing and other motoring costs increased.
The latest figures are particularly relevant to London employees who use their personal vehicles to visit customers, travel between workplaces or attend temporary work locations, as well as tradespeople, contractors, company directors and self-employed workers.
HMRC has also introduced updated company-car advisory fuel rates from 1 September 2026, meaning drivers need to distinguish between using their own vehicle and driving a company vehicle before calculating a claim.
What Are The HMRC Mileage Rates For 2026?
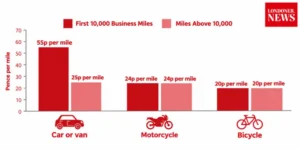
For the 2026/27 tax year, HMRC’s approved mileage rates are:
| Vehicle | First 10,000 Business Miles | Miles Above 10,000 |
| Car or van | 55p per mile | 25p per mile |
| Motorcycle | 24p per mile | 24p per mile |
| Bicycle | 20p per mile | 20p per mile |
Employees using their own car or van can also receive an additional 5p per passenger per business mile when carrying fellow employees on qualifying business journeys.
The higher 55p rate represents an increase of 10p per mile compared with the previous 45p rate.
Someone completing 5,000 qualifying business miles in their own car, for example, has an approved mileage amount of:
5,000 × 55p = £2,750
Under the previous 45p rate, the equivalent amount would have been £2,250.
At exactly 10,000 qualifying miles, the approved amount is now £5,500, compared with £4,500 under the old rate.
For someone driving 12,000 qualifying miles, the calculation would be:
10,000 × 55p = £5,500
2,000 × 25p = £500
Total approved mileage amount = £6,000
The important point for workers is that the HMRC figure is not necessarily the amount an employer must pay.
Employers can reimburse at a lower rate unless a contract or workplace policy says otherwise.
The HMRC-approved rate primarily sets the amount that can generally be paid without Income Tax becoming due under the approved mileage allowance rules.
If an employer pays less than the approved rate, an employee may be able to claim Mileage Allowance Relief on the difference.
For example, an employee travelling 4,000 qualifying business miles who receives 35p per mile from an employer would receive £1,400.
The HMRC-approved amount would be £2,200.
That leaves an £800 difference on which the employee may be entitled to tax relief. A basic-rate taxpayer obtaining relief at 20% would potentially save £160 rather than receiving the whole £800 directly.
HMRC confirms that workers claiming vehicle expenses must distinguish genuine business travel from ordinary commuting. A normal journey between home and a permanent workplace generally does not qualify.
The higher allowance was welcomed by consumer finance expert Martin Lewis, who described the increase as a “really important” change for people who have to drive as part of their work.
He also highlighted that employees paid below the HMRC rate can potentially claim tax relief on the difference.
However, some tax specialists argue that the increase has not fully caught up with the rise in motoring costs.
Jon Stride, chair of the Association of Taxation Technicians’ Technical Steering Group, said:
“The increase to 55p per mile is welcome and long overdue.”
The ATT said fuel, insurance, vehicle and servicing costs have risen substantially since the previous rate was introduced and criticised the decision to leave the 25p rate for mileage above 10,000 miles unchanged.
Transport policy experts have made a similar point. Steve Gooding, director of the RAC Foundation, said the increase was particularly positive for lower-income workers required to use their own vehicles, although the organisation’s analysis suggested that a gap remains between the allowance and wider motoring costs.
The Government estimated when announcing the change that around two million employees and one million self-employed people could benefit.
It also said a worker completing 6,000 qualifying business miles could save more than £120 a year as a result of the change.
Company Car Mileage Rates Changed Again In September
One area likely to cause confusion is the difference between the 55p approved mileage rate and HMRC’s Advisory Fuel Rates.
The 55p figure generally relates to employees using their own car or van for qualifying business travel.
When an employee is using a company car, separate advisory fuel rates normally apply when an employer reimburses business fuel or when an employee repays the cost of private fuel.
HMRC’s latest company-car rates took effect on 1 September 2026.
For petrol and LPG vehicles:
| Engine Size | Petrol | LPG |
| 1,400cc or less | 14p | 11p |
| 1,401cc to 2,000cc | 17p | 13p |
| Over 2,000cc | 27p | 20p |
For diesel company cars:
| Engine Size | Diesel |
| 1,600cc or less | 15p |
| 1,601cc to 2,000cc | 16p |
| Over 2,000cc | 22p |
Hybrid company cars are treated as either petrol or diesel vehicles for these rates.
Electric company cars now have separate rates depending on where they are charged.
From 1 September 2026, HMRC’s advisory electricity rates are:
- 7p per mile for home charging
- 15p per mile for public charging
This means an employee driving their own fully electric car should not automatically use the 7p or 15p company-car figures.
HMRC classifies electric and hybrid cars and vans owned personally by employees within the normal car and van mileage category, so qualifying mileage can use the 55p rate for the first 10,000 miles and 25p thereafter.
The 7p and 15p figures relate to fully electric company cars.
HMRC also says a higher company-car electricity reimbursement can be used where an employer can demonstrate that the actual electricity cost per mile was higher.
Where charging takes place both at home and at public chargers, mileage can be apportioned on a fair and reasonable basis.
Self-Employed Workers Can Also Use The Higher Rate
The change is not limited to employees.
Eligible self-employed people who calculate vehicle costs using HMRC’s simplified expenses method can also use the increased mileage rate.
For 2026/27 that means:
Cars and goods vehicles: 55p for the first 10,000 business miles and 25p thereafter.
Motorcycles: 24p per qualifying business mile.
Instead of separately calculating the business proportion of costs such as fuel, servicing, repairs and insurance, the simplified method allows eligible businesses to calculate a deduction from qualifying mileage.
Josh Toovey of IPSE, the organisation representing self-employed workers, noted that the previous 45p rate had been frozen since 2011 while fuel, insurance and general vehicle-running costs had increased.
IPSE calculated that a self-employed worker completing 6,000 qualifying business miles would receive a £3,300 deduction against taxable profit using the new rate, compared with £2,700 under the previous system.
That represents an additional £600 deduction.
The retrospective nature of the change is particularly important.
Although the higher figure was announced in May and detailed in an HMRC policy paper in June, the increase applies from 6 April 2026.
Businesses that reimbursed eligible mileage at the old 45p rate during the early part of the tax year can therefore review those payments.
The Association of Taxation Technicians says employers can potentially pay the difference between 45p and 55p for qualifying mileage since 6 April without Income Tax and National Insurance becoming payable on that additional amount.
Employees should also keep accurate mileage records.
HMRC says mileage logs used to support claims should include information such as the purpose of the journey and the starting and finishing postcodes.
Workers should therefore record journeys as they happen rather than trying to reconstruct several months of business travel later.
For London workers, the distinction between business travel and commuting can be especially important.
Driving from home to a normal permanent office generally does not become qualifying business mileage simply because the employee needs a car for work later in the day.
Journeys between workplaces, visits to customers and travel to qualifying temporary workplaces can be treated differently depending on the circumstances.
As of 21 September 2026, the main HMRC mileage figure for someone using their own car or van therefore remains 55p per mile for the first 10,000 qualifying business miles, falling to 25p after that point.
For company-car users, the calculation is different, with HMRC’s latest petrol, diesel, LPG and electricity rates applying from 1 September 2026.
The Government has also committed to reviewing mileage rates beyond 2026/27, so another decision on the system could follow as part of the Budget process.
About the Journalist
Olivia covers London life, culture and lifestyle for Londoner. Her work includes food, shopping, neighbourhood trends, attractions, local experiences and practical guides for residents and visitors. She focuses on engaging stories that reflect everyday life across the capital.