UK Retirement Annuity Payout Trends: Rates Climb As Retirees Secure Higher Income
 Published By
Lucy
Published:
Updated:
UK pension savers approaching retirement are being offered some of the strongest annuity payouts seen in years, as rising government bond yields continue to reshape the retirement income market.
The latest UK retirement annuity payout trends show that a £100,000 pension pot can now generate more than £8,000 a year in some circumstances for a healthy 65-year-old choosing a single-life level annuity.
Hargreaves Lansdown’s market comparison on 27 August showed a 65-year-old could receive as much as £8,077 a year from £100,000 with a single-life level annuity without a guarantee period. Adding a five-year guarantee reduced the leading figure slightly to £8,014.
By comparison, the equivalent highest payout for a 70-year-old was £8,851, demonstrating how age remains one of the biggest factors determining retirement income.
The improvement has accelerated as UK government bond yields have climbed. Long-dated gilt yields, which play an important role in how insurers price annuities, reached multi-decade highs at the beginning of September.
Analysis published on 3 September said a healthy 65-year-old could secure just over £8,000 from £100,000 under certain annuity terms, compared with less than £5,000 during lows seen around a decade ago.
Standard Life’s separate tracker found that the average rate for a healthy 65-year-old had risen to 7.75% in July 2026, its highest level since August 2008. The equivalent rate was 7.66% in April.
Annuities Are Also Making a Comeback
Higher payouts appear to be encouraging more pension holders to reconsider guaranteed retirement income after years in which pension drawdown became increasingly popular.
The FCA’s latest retirement income market data shows 88,430 annuities were sold in 2024/25, up 7.8% from 82,061 the previous year. That followed an even larger 38.7% rise in annuity sales during 2023/24.
Drawdown has not disappeared, however. FCA figures show drawdown policy sales jumped 25.5% to 349,992 during 2024/25.
That suggests the emerging retirement trend is not simply a move away from drawdown. Some pensioners are instead using guaranteed annuity income alongside more flexible pension arrangements.
For London workers approaching retirement, the timing is particularly relevant because the UK’s State Pension age is already rising from 66 to 67 between April 2026 and March 2028.
Why Two £100,000 Pension Pots Can Produce Different Payouts?
Headline annuity rates do not tell the whole story.
The eventual amount someone receives can depend on:
- Age – older buyers will generally be offered higher annual income.
- Health and lifestyle – medical conditions or smoking can qualify someone for an enhanced annuity.
- Single or joint life – providing continuing income for a partner normally reduces the starting payout.
- Guarantee periods – protecting payments for a minimum period can affect the rate.
- Inflation protection – escalating annuities usually begin with considerably lower payments than level annuities.
- Provider competing insurers can quote noticeably different incomes for the same pension pot.
This is an important gap in headline comparisons. A high level-annuity payout may look attractive today, but its purchasing power can gradually fall if inflation continues while the payment remains unchanged.
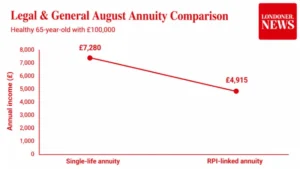
Legal & General’s August data illustrates the difference. For a healthy 65-year-old with £100,000, its example single-life annuity provided £7,280 annually, while an RPI-linked equivalent started at £4,915.
There are also tax considerations. Annuity payments from pension savings are generally treated as taxable pension income, meaning retirees need to consider their State Pension and other income when calculating their overall tax position.
Londoners have separately examined how pension income can interact with savings interest and tax allowances.
The latest figures therefore point to a significant shift in the UK retirement market: annuities are once again capable of producing historically strong guaranteed incomes.
But the best headline rate will not automatically be the best retirement deal.
With differences between providers, enhanced rates, inflation protection and partner benefits potentially affecting income for decades, comparing the whole market remains increasingly important before pension savings are permanently converted into an annuity.
About the Journalist
Lucy reports on London’s boroughs and the capital’s sporting community. Her coverage includes council decisions, neighbourhood developments, community issues, football, tennis, cricket and major sporting events. She focuses on stories that connect local communities and highlight the people and organisations shaping London.